

TD Bank (US)
by TD Bank, N.A.
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
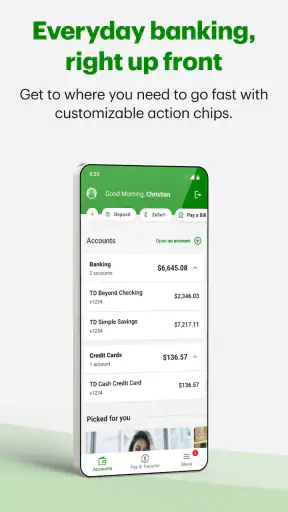
Managing everyday banking from a phone sounds simple until a banking app makes routine tasks feel scattered or slow. TD Bank takes a more practical approach: it puts the main parts of a TD customer’s daily banking in one mobile place. After spending time with the app, I found that its biggest value is not flashy presentation but the way it reduces the need to switch between separate banking tasks. Checking an account, reviewing recent activity, moving money, and handling ordinary financial errands can all begin from the same screen.
That focus makes this a useful personal finance app for people who already bank with TD Bank, N.A. It is free, aimed at Everyone, and available for Android and iOS devices that meet its operating-system requirement. The app has been around since 2010, and its current version is 26.10.1.71. With an average rating of 4.2 from roughly 90 thousand ratings and more than 5 million installs, it is clearly used as a regular banking tool rather than an occasional novelty.
One place for everyday banking
The capability I kept returning to was the app’s all-in-one approach to routine account management. Instead of treating checking, savings, transfers, and account activity as unrelated destinations, TD Bank presents them as parts of the same banking workflow. That matters because most people do not open a banking app to explore; they open it with a specific question or task in mind.
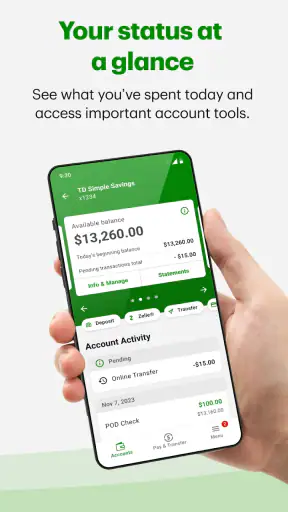
When I wanted to know whether a payment had cleared, I did not need a separate budgeting product or a desktop session just to get a basic answer. The app is built around that quick check: open it, identify the relevant account, and inspect the latest activity. The same central setup is useful when the task changes from checking information to taking action.
The real strength is reduced friction between seeing your money and deciding what to do with it. A balance by itself is not very helpful if it is disconnected from recent transactions or the next banking action. TD Bank keeps those steps close together, which makes it easier to use the app during small moments throughout the day.
This is different from a standalone budgeting app. Budgeting tools can be better for long-term categories, spending trends, and detailed planning, while TD Bank is more directly tied to the practical relationship between you and your bank. I would use a budgeting app alongside it if I wanted a broader view across several financial institutions. I would not expect TD Bank to replace every specialized money-management tool.
What the unified design changes in practice
The first useful change is context. If I check an account and immediately notice an unfamiliar or larger-than-expected transaction, I am already looking at the place where that activity belongs. I do not have to remember which account was involved or reconstruct the situation from a separate service. That may sound minor, but it makes quick financial checks less mentally demanding.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The second change is convenience for people who bank in short sessions. I might open the app while waiting for a coffee, before paying a bill, or after receiving a notification from a merchant. In those moments, a compact banking workflow is more valuable than a large collection of advanced financial tools. TD Bank feels designed for repeated, ordinary visits rather than one long monthly review.
The third change is confidence when moving money between familiar accounts. The ability to view the accounts and then continue into a transaction-related task from the same banking environment helps reduce the chance of acting on outdated information from memory. I still recommend pausing before confirming anything, especially when several accounts have similar names or purposes, but the app supports a more deliberate process than relying on handwritten notes or remembered balances.
How I would use it during a normal week
On a typical morning, I would use the app first as a visibility tool. I would check the available balance, scan recent activity, and look for anything that needs attention before making a purchase. That is a better habit than checking only the headline balance, because pending or recent activity can change how much money is realistically available for the day.
Later, I might return to handle a planned transfer or verify that an expected transaction appeared. The useful detail here is the separation between checking and acting: I can review what happened before deciding what should happen next. That small pause is one of the app’s practical benefits, particularly for users who tend to manage money quickly from a phone.
At the end of the week, I would use the activity view as a lightweight spending review. It is not a replacement for a detailed financial plan, but it can reveal recurring purchases, forgotten subscriptions, or an unusually expensive day. My advice is to treat this as a short diagnostic routine: scan for things that require action, rather than trying to turn every visit into a full budgeting session.
A realistic emergency use case
Imagine that I am about to make a rent payment and notice that a recent purchase is larger than expected. The important question is not simply “What is my balance?” but “Which transactions have actually affected this account, and do I need to move money before making the payment?” With TD Bank, I can begin by checking the account activity, compare it with what I remember spending, and then decide whether a transfer or another banking step is appropriate.
That workflow is especially helpful when the issue is uncertainty rather than a complex financial problem. I am not trying to build an investment strategy from the app. I am trying to avoid an avoidable mistake in the next few minutes. The app’s value is strongest in exactly those modest but consequential decisions.
Where the experience has limits
The all-in-one design does not automatically make every banking task effortless. A single app can feel convenient when I know what I want, but it can also feel dense when several account types, transactions, or actions appear together. New users may need a little time to understand where each routine belongs, especially if they rarely use mobile banking.
There is also a trade-off between convenience and concentration. Keeping banking tasks in one app means the experience is efficient for TD customers, but it is less useful as a neutral overview of finances held elsewhere. If my accounts are spread across multiple banks, I would still need another method to see the complete picture. In that situation, a multi-institution finance service may be better for overview, while TD Bank remains the right tool for direct TD account management.
I also would not choose it as my only financial planning tool. Someone who wants deep spending analysis, investment research, debt payoff projections, or extensive goal tracking may find a dedicated service more suitable. TD Bank is strongest at everyday banking actions and account awareness, not at turning a phone into a complete financial command center.
Small habits that make the app more useful
My first tip is to open the app before making a significant payment, not after. Checking recent activity first gives me a more realistic picture of the account and makes the next action less impulsive. This is particularly useful when several purchases have happened since the last time I looked.
My second tip is to use transaction review as an early warning habit. I would not wait until the end of the month to look for problems. A short scan after a busy shopping day can catch an unexpected charge while the details are still fresh. That makes it easier to distinguish a genuine mistake from a purchase I simply forgot about.
My third tip is to separate routine use from financial planning. I would use TD Bank for checking, account activity, and ordinary banking actions, then use a broader planning tool if I needed categories, forecasts, or a combined view of several institutions. Expecting one banking app to perform every financial job can make the experience feel weaker than it really is.
A fourth useful habit is to avoid treating a displayed balance as permission to spend immediately. The app gives me important account information, but responsible use still requires reading the activity and considering upcoming obligations. The technology can make the check faster; it cannot make the financial decision for me.
Who benefits most from this approach
TD Bank is a strong fit for existing TD customers who want a straightforward mobile route to everyday banking. It suits people who regularly check their accounts, review activity, and handle routine money movement from a smartphone. It is also a sensible choice for users who prefer dealing directly with their bank rather than connecting their finances to a separate aggregation service.
I think it is particularly useful for people whose financial lives are relatively organized around TD accounts. The fewer institutions and specialized tools I need to coordinate, the more the app’s unified approach pays off. It can also help users who are trying to develop a habit of checking activity before spending, because that information is close at hand instead of hidden behind a desktop-only workflow.
Families and shared households may also appreciate the convenience of quick account checks, although the usefulness depends on how each person manages access and responsibilities. I would recommend agreeing on who reviews activity and who initiates transactions rather than assuming that mobile access alone will solve communication problems. The app can support a household routine, but it does not replace one.
On the other hand, I would steer away from it if I wanted a bank-neutral dashboard, a serious budgeting workspace, or detailed investment analysis. Someone who does not bank with TD will gain little from an app centered on TD’s own services. Likewise, users who prefer managing money exclusively on a computer may not find a mobile-first workflow compelling, even though having a phone option is convenient for many people.
How it compares with familiar alternatives
Compared with visiting a bank website in a mobile browser, a dedicated app feels more natural for repeated checks. The experience is built around a phone rather than a smaller version of a desktop page, so it better suits quick account reviews and short banking sessions. I still prefer a larger screen for complicated financial paperwork or careful document review, but the app is more convenient for ordinary account awareness.
Compared with a spreadsheet, TD Bank is better for checking current banking activity because I do not have to enter every transaction manually. A spreadsheet remains better for custom calculations, household planning, and scenarios that require my own structure. I see the two as complementary: the app supplies the banking view, while the spreadsheet can turn that information into a personal plan.
Compared with an independent budgeting app, TD Bank offers a more direct connection to TD banking tasks but a narrower financial perspective. A budgeting service may be better when I want accounts from different institutions in one place or need more elaborate spending organization. The trade-off is that a separate service can add another layer between me and the bank. For direct TD account work, the bank’s own app is the more natural starting point.
Its 4.2 average rating and broad adoption suggest that many people find the overall experience dependable enough for regular use, but those figures should not replace personal testing. Banking needs vary, and the right question is whether the app handles the tasks I perform most often without making me work around its layout or limits.
Security-minded use and everyday responsibility
Because this is a finance app, I would approach it differently from a shopping or entertainment download. I would install it only on a device I control, keep the phone’s operating system current, and avoid handling sensitive banking tasks on an untrusted network. Those are not special features of TD Bank; they are sensible habits whenever an app gives access to financial information.
I would also review every transfer or payment carefully before confirming it. The convenience of a unified app can make actions feel quick, and quick is not always the same as careful. A good routine is to verify the account, recipient or destination, and amount before completing the final step. That extra moment is worthwhile when a mistake could affect rent, bills, or a shared household account.
For someone concerned about whether the app will suit an older family member, I would focus less on the number of features and more on the person’s comfort with mobile navigation. The app can simplify access by bringing banking into one place, but a user unfamiliar with phone-based banking may still need a guided first session. I would begin with account viewing before introducing money movement.
My recommendation after using it
TD Bank works best as a dependable daily banking companion, not as an all-purpose financial planning suite. I like it because its central capability has a clear effect: it brings account awareness and routine banking actions into the same mobile experience. That makes short, real-life decisions easier, from checking whether a payment cleared to reviewing activity before spending.
The limitations are equally clear. It is tied to TD banking, it does not replace a broader cross-bank financial dashboard, and users seeking deep budgeting or investment tools may need something else. Those are not reasons to dismiss it; they simply define the app properly. It is most valuable when the goal is direct, frequent, everyday management rather than comprehensive financial analysis.
For TD customers who want a free mobile way to stay close to their accounts, I would recommend giving it a try. The app is available for users on operating system version 12 or later, and its Everyone age rating makes it broadly approachable. My advice is to judge it by the tasks that matter most to you: checking activity, understanding your current position, and completing routine banking without unnecessary detours.
After using it in that context, I came away with a favorable but measured view. TD Bank earns its place on my phone when I need practical access to my bank, not when I want a complete financial strategy. If that distinction matches your needs, its focused, all-in-one design can make everyday banking noticeably easier.
Pros
- Clear overview of balances, transactions, and account activity
- Mobile check deposit is convenient for eligible accounts
- Bill Pay helps manage recurring payments in one place
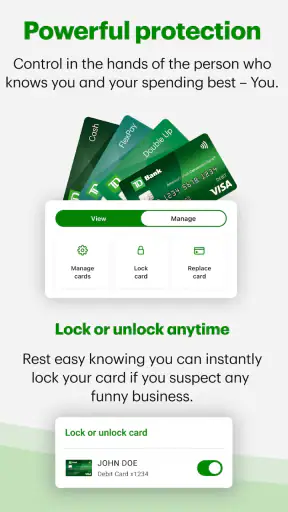
- Card controls can help monitor or restrict debit card usage
- Branch and ATM locator makes finding nearby services easy
Cons
- Some features may require enrollment or an eligible TD account
- Mobile deposit limits can vary by customer and account history
- App performance may depend on device and internet connection
- Certain support requests may still require contacting the bank
- International banking features may be limited compared with larger banks
FAQs for TD Bank (US)
What is TD Bank, and what can I do with its mobile app?
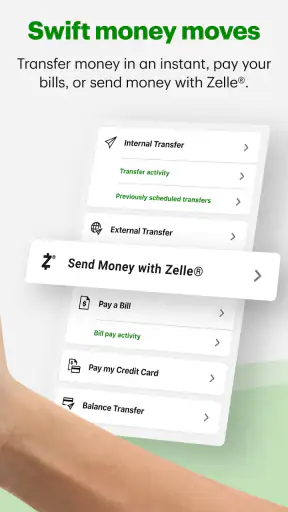
TD Bank is a U.S. financial institution offering checking and savings accounts, credit cards, personal loans, mortgages, and other banking services. Its mobile app lets customers review balances and transactions, transfer money, deposit eligible checks, pay bills, send money with Zelle, locate branches and ATMs, manage alerts, and contact support. Available tools can vary depending on your account type and location.
Is the TD Bank mobile app safe to use for banking?
The TD Bank app includes security features designed to protect your account, such as encrypted connections, secure login options, biometric authentication on compatible devices, fraud monitoring, and account alerts. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your phone updated, avoid public Wi-Fi for sensitive activity, and never share passwords or verification codes.
Can I deposit checks and transfer money through TD Bank?
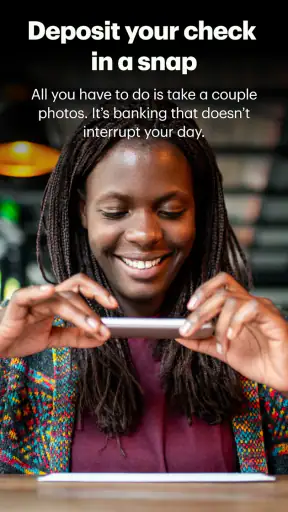
Yes, eligible customers can generally use TD Bank’s mobile check deposit feature by photographing the front and back of a properly endorsed check. The app also supports transfers between eligible TD accounts and may allow external account transfers, depending on enrollment and account settings. Deposit limits, processing times, holds, transfer availability, and applicable fees can differ, so review the terms shown in the app.
Does the TD Bank app charge fees for its services?
Downloading the TD Bank app is generally free, but using certain banking services may involve account-specific fees. Possible charges can include monthly maintenance fees, overdraft-related fees, out-of-network ATM fees, wire transfer costs, or fees associated with particular transactions. Some customers may qualify for waivers based on account balances, direct deposits, or other requirements. Always check the current fee schedule before relying on a feature.
What should I do if I cannot log in or notice suspicious activity?
If you cannot access your account, first verify your username, password, internet connection, and app version, then use the official password-recovery options rather than third-party websites. If you see an unfamiliar transaction, receive an unexpected security message, or suspect fraud, contact TD Bank immediately through the verified app, official website, or the phone number on your card. Never provide login credentials or one-time codes to unsolicited callers.

TD Bank (US)
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via Mobile@td.com, visit http://www.tdbank.com, or review their http://www.tdbank.com/bank/privacy_and_security.html.










